Vans
Small, medium and large vans used for parcel and freight delivery. See our van insurance page for more on van cover.
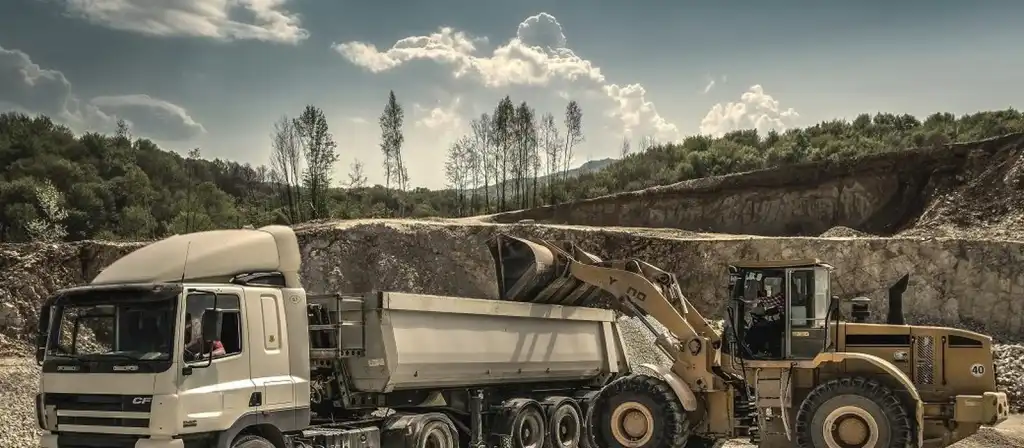
Insuregroup arranges insurance for couriers and delivery businesses across Australia: vans, utes and small trucks, the goods you carry, public liability and cover for owner-drivers who cannot work.
Insuregroup arranges insurance for couriers and delivery businesses across Australia, from sole traders with one van or ute to fleets of vans and small trucks doing parcel, freight and last-mile work. We look at the vehicle, the goods you carry and the contracts you work under, and compare options across our network of insurers.
Courier work puts a lot of kilometres, stops and customer premises into a single day. That mix is why a private car policy, or a commercial policy set up for different work, may not respond the way you expect.
Small, medium and large vans used for parcel and freight delivery. See our van insurance page for more on van cover.
Single and dual cab utes, including those with canopies or trays fitted for delivery work.
Pantechs, box trucks and pod trucks used for pallet and bulky deliveries. See truck insurance Australia.
Temperature-controlled vans for food, pharmaceutical and florist deliveries. Ask about refrigeration breakdown cover for the goods. See refrigerated truck insurance.
Vans, utes and small trucks on one program as the business grows. See commercial vehicle insurance and fleet insurance.
Covers accidental damage to your vehicle, theft, and your legal liability for damage to other people’s vehicles and property, subject to the policy terms. It should be set up for courier use, with the right radius and drivers declared.
Covers the parcels and freight you carry against loss or damage, or your liability to the owner of those goods. Check the limit per vehicle against your highest-value loads. See transit insurance.
Covers your legal liability for injury to people or damage to property while you are working, for example at a customer’s door or on a loading dock. Many contracts set a minimum limit. See public liability insurance.
If you are a sole trader, workers compensation does not usually cover you. Personal accident and illness cover can pay a weekly benefit if an injury or illness stops you working. See personal accident insurance.
Trolleys, scanners, phones and other portable equipment may need separate cover, as they are not usually part of a motor policy.
Insurers ask how a vehicle is used because it changes the risk. Courier and delivery work involves carrying goods for others, frequent stops and long hours on the road. A policy set up for private use, or for general business use, may restrict or exclude that kind of work.
Our article on hire and reward vs private use explains why declared use matters at claim time.
Many courier contracts and delivery platforms set out the insurance a contractor must hold. Requirements vary, but commonly include:
Send us the insurance clause from your contract and we will check your policies against it. Our guide to subcontractor insurance requirements has more background.
There is no standard price. Our guide on what drives the cost of truck and commercial vehicle insurance explains how these factors work.
Always read the Product Disclosure Statement for the full terms. We can walk you through the exclusions that apply to your work.
Tell us about your vehicles, drivers, the work you do and any contract requirements. A broker will compare options across our network of insurers and explain the differences so you can decide. For vans and trucks, you can also use our online vehicle quote form.
Stirling set up Insuregroup in 2014 after many years as an insurance underwriter and broker. He oversees the day-to-day broking, negotiates with insurers for clients and helps with claims, for everyone from single-truck owner-drivers to large fleets of trucks and heavy plant.
Insuregroup have been very professional and prompt in dealing with the management of our insurances for the last 3 years.

Most couriers need commercial motor insurance set up for courier use, goods in transit or carrier's liability for the parcels they carry, and public liability. Sole traders should also consider personal accident and illness cover.
Not necessarily. A policy set up for private use, or for general business use, may restrict or exclude carrying goods for reward. Tell the insurer the vehicle is used for courier or delivery work.
Usually not. The goods are normally covered under a separate goods in transit or carrier's liability policy, with a limit per vehicle.
Many do. Requirements commonly include a minimum public liability limit, cover on the vehicle, goods in transit cover and a certificate of currency. Check your contract or platform terms, or send them to us to review.
Workers compensation does not usually cover sole traders for their own injuries. Personal accident and illness cover can pay a weekly benefit if you cannot work because of an injury or illness.
Yes. Once you run several vehicles, a fleet or commercial vehicle policy can cover them together, which can make renewals and adding vehicles simpler.
Tell us what you run and how you run it. We review the options across our insurer panel and come back with cover that fits — usually inside one business day.