Comprehensive
Covers accidental damage to your vehicle, fire and theft, and your legal liability for damage to other people’s vehicles and property, subject to the policy terms, limits and excess.
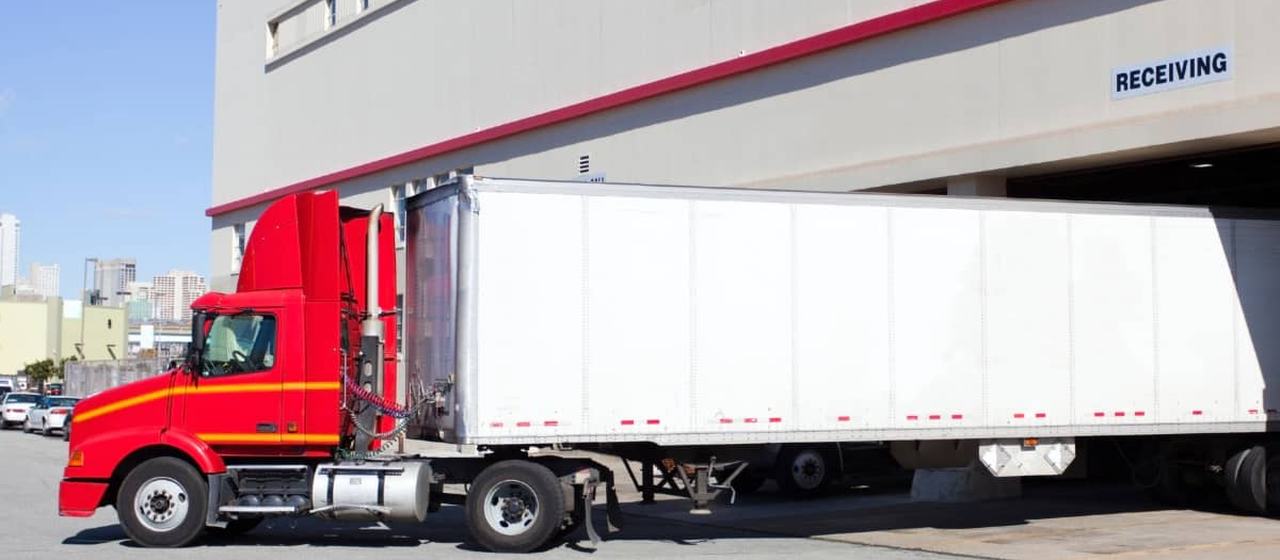
Insurance for heavy vehicles over 4.5 tonnes GVM, from single rigid trucks to prime movers, B-doubles, road trains and buses. We compare options across our network of insurers and specialist heavy motor underwriters.
Insuregroup is a specialist heavy vehicle and truck insurance broker. We arrange cover for owner-drivers, transport businesses and fleet operators running heavy vehicles across Australia, from single rigid trucks to prime movers, B-doubles and road trains. We look at how your vehicles are used and compare options across our network of insurers and specialist heavy motor underwriters.
Under the Heavy Vehicle National Law (HVNL), a heavy vehicle is generally a vehicle with a gross vehicle mass (GVM) or aggregate trailer mass (ATM) of more than 4.5 tonnes. Insurers often use a similar line to separate heavy motor policies from light commercial or van policies, although each insurer sets its own categories.
Heavy vehicles we commonly arrange cover for include:
Lighter vans and utes are usually insured under a light commercial motor policy instead. See commercial vehicle insurance for vans, utes and mixed fleets.
Covers accidental damage to your vehicle, fire and theft, and your legal liability for damage to other people’s vehicles and property, subject to the policy terms, limits and excess.
Covers fire and theft of your vehicle and your liability for damage you cause to others, but not accidental damage to your own vehicle.
Covers your legal liability for damage to other people’s vehicles and property only. It is sometimes chosen for older vehicles where comprehensive cover costs a lot compared with the vehicle’s value.
Compulsory Third Party (CTP) insurance covers injuries to other people caused by your vehicle and is required for registration. It does not cover damage to vehicles or property. In NSW it is bought as a Green Slip; in most other states it is paid with registration.
The HVNL applies in Queensland, New South Wales, Victoria, South Australia, Tasmania and the ACT, and is administered by the National Heavy Vehicle Regulator (NHVR). Western Australia and the Northern Territory have their own heavy vehicle laws. Mass and dimension limits, loading, fatigue management, vehicle standards and chain of responsibility duties all apply.
Insurance does not replace compliance. A breach can affect how a claim is assessed, and some policies exclude losses linked to unroadworthy or overloaded vehicles. Our guides explain the link:
One or two heavy vehicles are usually insured on individual policies. As the number of vehicles grows, a fleet policy can put every vehicle on one renewal date with consistent terms, and some insurers will rate the fleet on its overall claims record. The right point to move depends on the insurer and the mix of vehicles.
For more, see our guides on truck insurance costs in Australia and how linehaul and metro risk profiles differ.
Send your vehicle and operating details online or call our Brisbane office. A broker will review your operation, compare options across our network of insurers and explain the differences so you can decide. Our truck insurance quote checklist lists the details that help.
General advice warning: the information on this page is general in nature and does not take into account your objectives, financial situation or needs. Before deciding on any insurance product, consider whether it is right for you and read the relevant Product Disclosure Statement (PDS) and Target Market Determination (TMD), available from us or the insurer. Cover is subject to the insurer’s underwriting and policy terms.
Stirling set up Insuregroup in 2014 after many years as an insurance underwriter and broker. He oversees the day-to-day broking, negotiates with insurers for clients and helps with claims, for everyone from single-truck owner-drivers to large fleets of trucks and heavy plant.
Insuregroup have been very professional and prompt in dealing with the management of our insurances for the last 3 years.

Under the Heavy Vehicle National Law a heavy vehicle is generally one with a GVM or ATM over 4.5 tonnes. Insurers often use a similar line between heavy motor and light commercial policies, but each insurer sets its own categories.
No. CTP covers injuries to other people. It does not cover damage to your vehicle, other vehicles or property, which needs a commercial motor policy.
Trailers you own can usually be listed on the policy. Trailers you tow but do not own may need trailer in control cover. Tell us about every trailer you own or tow.
It can. Insurance does not replace compliance, and some policies exclude or limit cover for losses linked to overloading or unroadworthy vehicles. Read your PDS and ask us if you are unsure.
It depends on the insurer and your vehicles. As the number of vehicles grows, a fleet policy can bring them onto one renewal with consistent terms. A broker can compare individual and fleet options for you.
Tell us what you run and how you run it. We review the options across our insurer panel and come back with cover that fits — usually inside one business day.